The two largest IPOs in history look like twins.
Anthropic & SpaceX trade within 15% of each other’s market cap, generate within 10% of the same trailing revenue, & are valued on an identical forward multiple of 9.5x.12
| Metric | Anthropic | SpaceX |
|---|---|---|
| Market cap1 | $1.56t | $1.82t |
| Trailing revenue1 | $35.3b | $32.0b |
| Trailing gross margin13 | 22% | 62% |
| 2027 est. revenue2 | $137b | $181b |
| Implied growth to 2027 est.2 | 288% | 466% |
| EV / 2027 est. revenue2 | 9.5x | 9.5x |
Curiously, SpaceX is projected to grow 46% faster than Anthropic, yet the market pays the same 9.5x multiple for both.
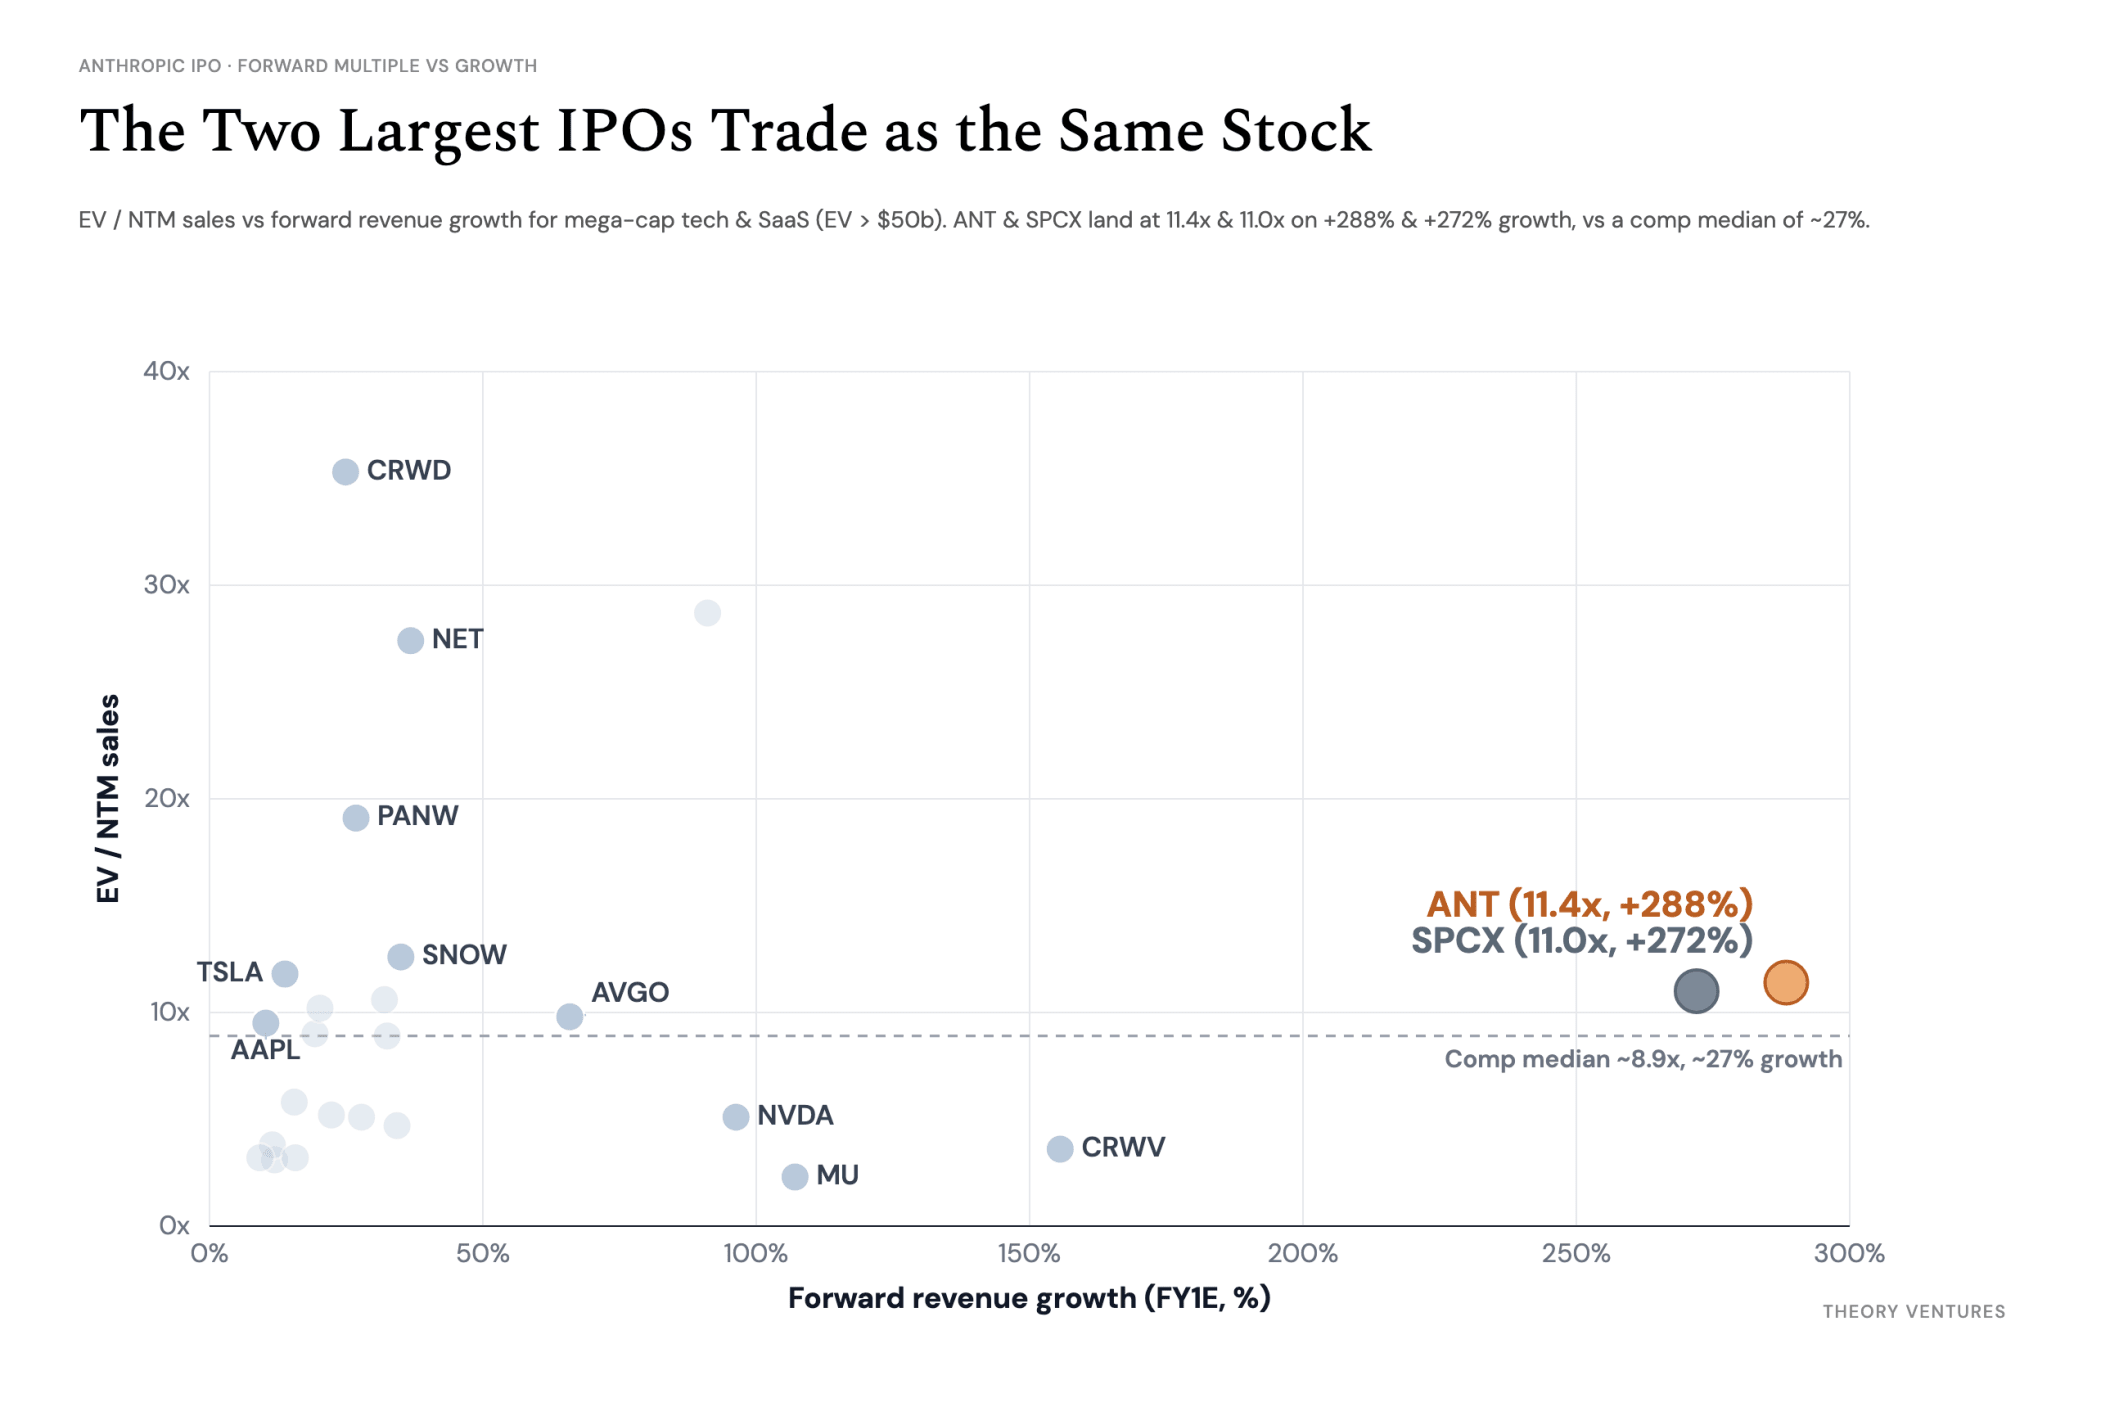
Across 24 mega-cap software & infrastructure names, both trade in the middle of the pack with roughly ten times the median growth.2
Even though both are growing faster than any software company in history, public markets are not valuing them on forward revenue multiples. They are valued like companies growing 20%, not 200%+.
Expand the lens to the trillion-dollar hyperscalers, & the ceiling is unmistakable : above $1t of enterprise value, no company trades much above 10x forward sales, regardless of whether it grows 16% or 466%.4
| Company | Enterprise value | Forward EV / sales | Forward growth | Gross margin | P/E |
|---|---|---|---|---|---|
| Anthropic12 | $1.30t | 9.5x | 288% | 22% | N/M |
| SpaceX12 | $1.71t | 9.5x | 466% | 62% | N/M |
| Microsoft4 | $3.73t | 9.0x | 19% | 68% | 26x |
| Google4 | $3.24t | 5.1x | 27% | 61% | 20x |
| Meta4 | $1.50t | 5.1x | 28% | 81% | 20x |
| Amazon4 | $2.94t | 3.2x | 16% | 51% | 22x |
P/E is the real anchor. Every trillion-dollar hyperscaler trades in a tight 20x to 26x earnings band. At Microsoft’s 41% net margin, 26x earnings caps forward revenue near 10x ; at Meta & Google’s margins, 20x earnings caps it near 5x.4
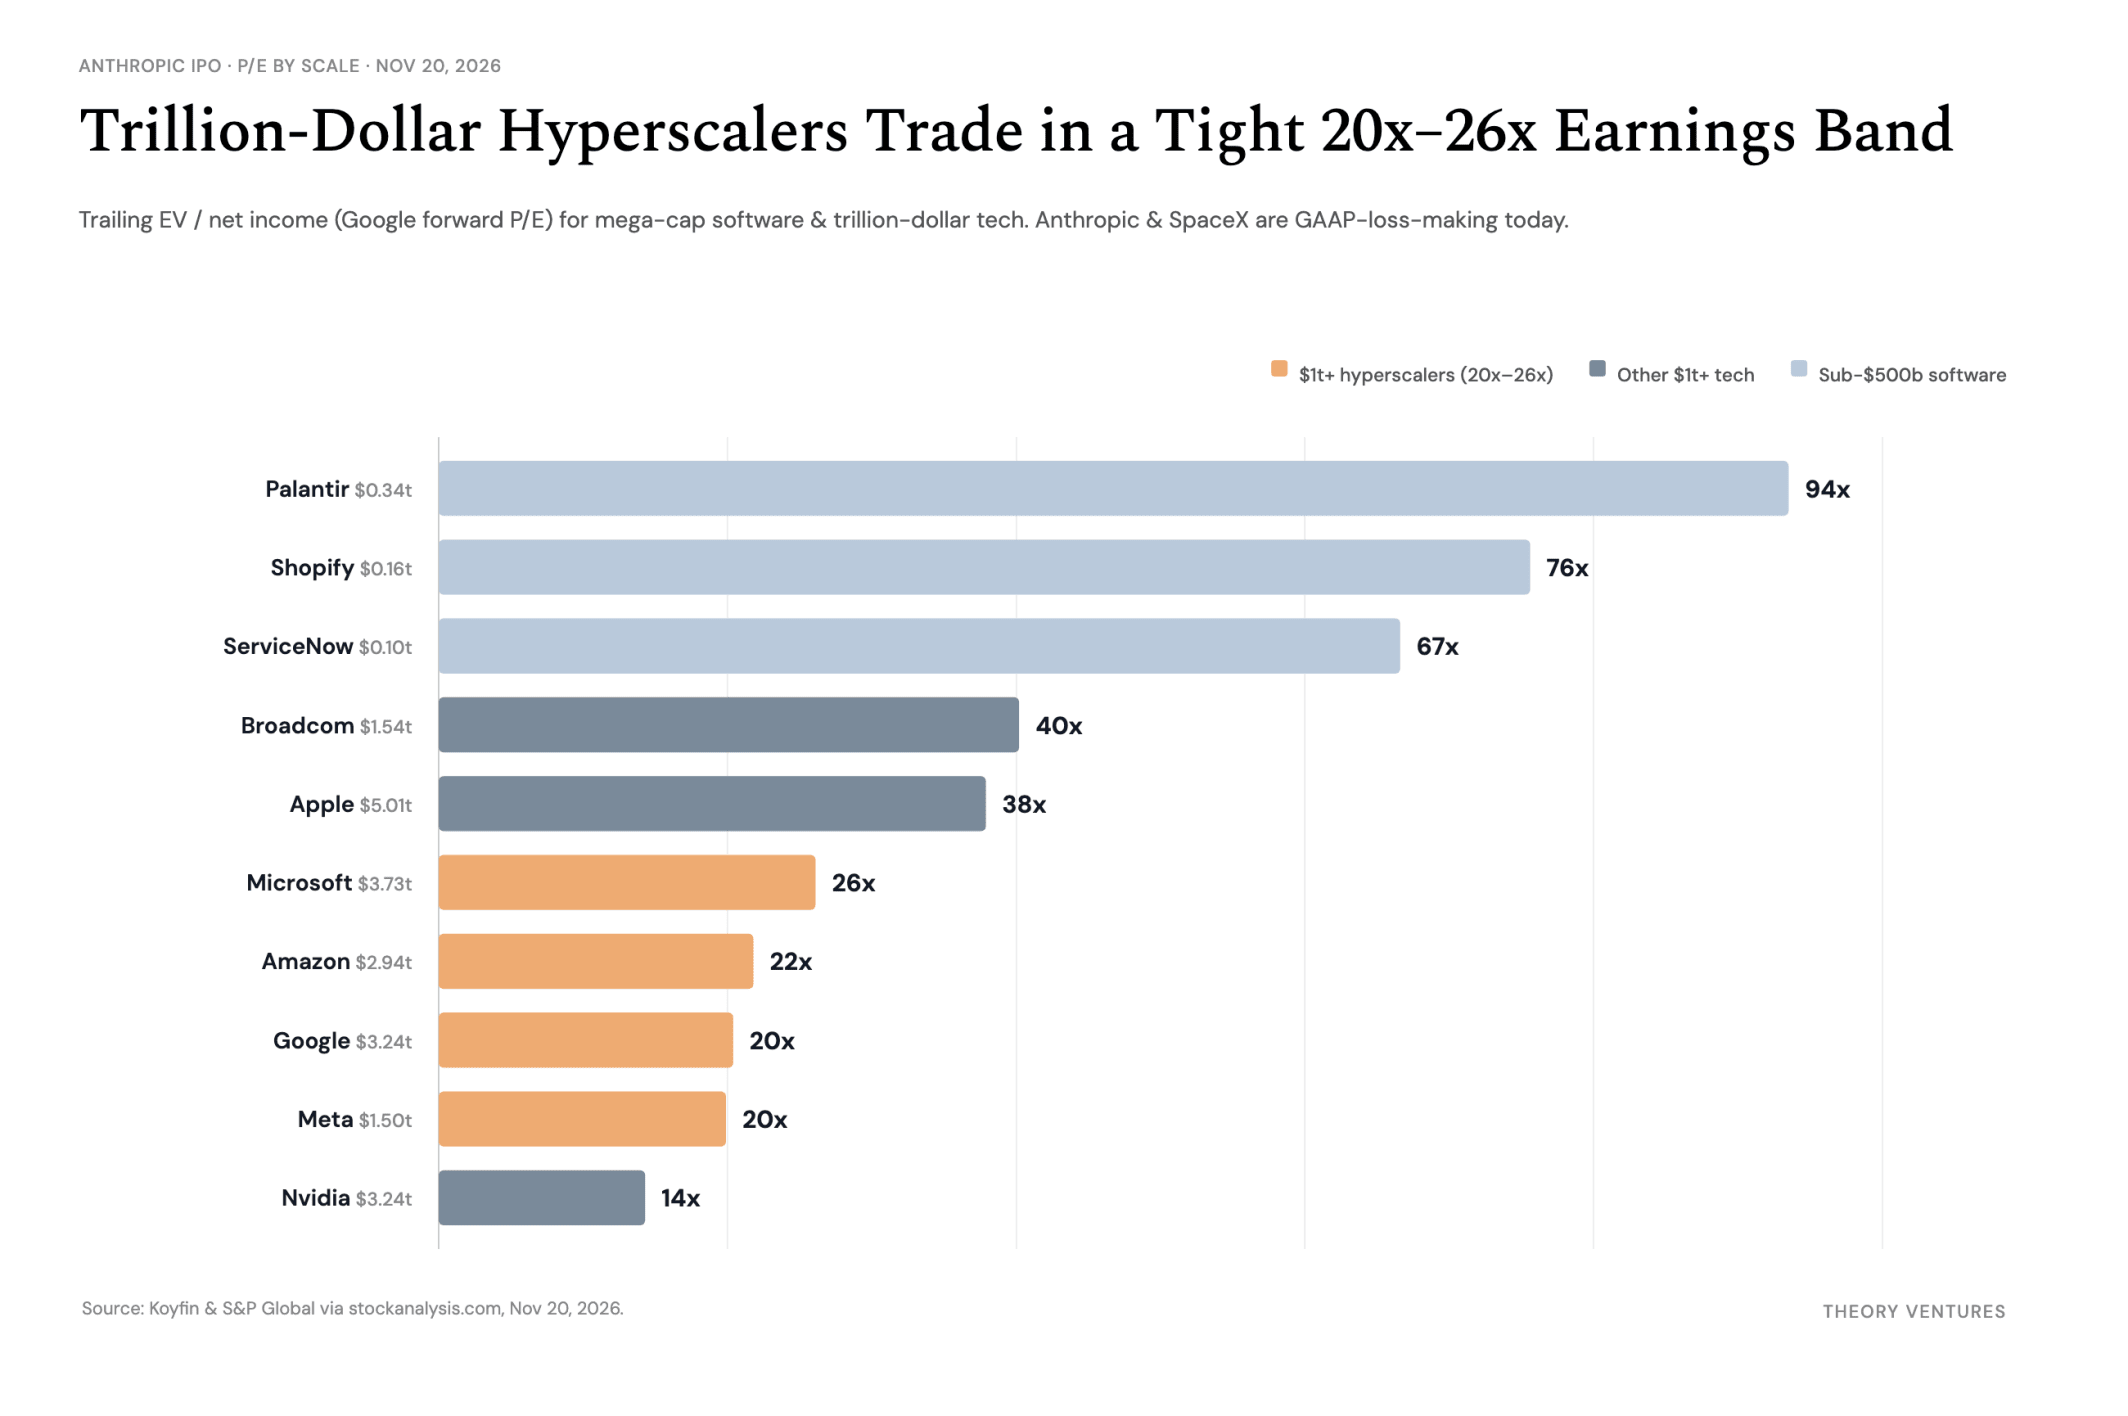
Public markets are not debating whether Anthropic or SpaceX is the better business : at trillion-dollar scale, multiple expansion is over, & the only way either stock compounds is by growing into the earnings.
-
Anthropic trades near $86 a share, about $1.56t of market value & $1.30t of enterprise value after $254b of net cash, against SpaceX’s $1.82t market value & $1.71t enterprise value : Koyfin & exchange data, November 20, 2026. Trailing revenue : Anthropic $35.3b & trailing gross margin 22% per Koyfin ; SpaceX $32.0b for the twelve months ended September 30, 2026, per its Form 10-Q. ↩︎ ↩︎ ↩︎ ↩︎ ↩︎ ↩︎
-
Forward 2027 est. : SpaceX’s $1.71t enterprise value against $181b of 2027 consensus revenue, or 9.45x, & Anthropic’s $1.30t against a $137b street estimate, or 9.49x, per S&P Global via stockanalysis.com & CNBC. Implied growth from trailing revenue : 466% for SpaceX & 288% for Anthropic. The scatter chart plots next-twelve-month multiples, where both land near 11x ; SpaceX’s dot uses consensus estimates, as Koyfin does not cover it. ↩︎ ↩︎ ↩︎ ↩︎ ↩︎ ↩︎ ↩︎
-
SpaceX Form 10-Q for the quarter ended September 30, 2026 : nine-month gross margin 62% : https://www.sec.gov/Archives/edgar/data/1181412/000162828026066880/spcx-20260930.htm ↩︎
-
Microsoft, Meta & Amazon enterprise value, next-twelve-month EV to sales, forward growth, trailing gross margin & trailing EV to net income per Koyfin, November 20, 2026. Alphabet enterprise value of $3.24t, 2027 consensus revenue of $636b, 27% forward growth, 61% trailing gross margin & 20.4x forward P/E per S&P Global via stockanalysis.com, November 20, 2026. Pure hardware trillion-dollar companies such as Nvidia, at 5.1x forward sales, & Tesla, at 11.8x, are excluded from the hyperscaler table. ↩︎ ↩︎ ↩︎ ↩︎ ↩︎ ↩︎