The Macroeconomic Signal to Watch for Software & Infrastructure Startups

As we navigate this bear market, I’m keeping my eye on broader market data points. A broad software buyer index would be the best metric to understand how buyer preferences are changing across the market. Fortunately, it exists.

Large SaaS and IaaS vendors are precisely that: indexes of software buyers. Amazon Web Services and Azure, the business units inside Amazon and Microsoft serve and sell to small, medium, and large companies in every major geography. So do Salesforce. ServiceNow. Adobe. Palo Alto Networks.

Read more

Office Hours for 2022 Market Conditions Market Survey Results

This Friday, June 3rd at 10:30am Pacific/1:30pm Eastern, I’ll be hosting Office Hours to review the 2022 Market Conditions Market Survey results. If you’d like to attend, please register here.

The session will review the top 10 learnings from the data across the hundreds of respondents and answer questions including:

  • how does the typical founder feel about the market?
  • how often are founders considering layoffs, inside rounds, and venture debt?
  • how will fundraising prices change, according to founders?
  • which segments of the market are witnessing changes to their sales cycles?
  • what does all this data imply for the market in the next 1-2 quarters for founders?

Attendees can submit questions ahead of time via the registration form or ask questions live during Office Hours.

Read more

The Largest Software Acquisition in History

Yesterday, Broadcom announced it will acquire VMWare for $70b, the largest software acquisition in history.

Remarkably, this goliath union transpires during the deepest bear market of the last ten years. This merger also suggests a wave of acquisitions may punctuate 2022, in particular, take-privates.

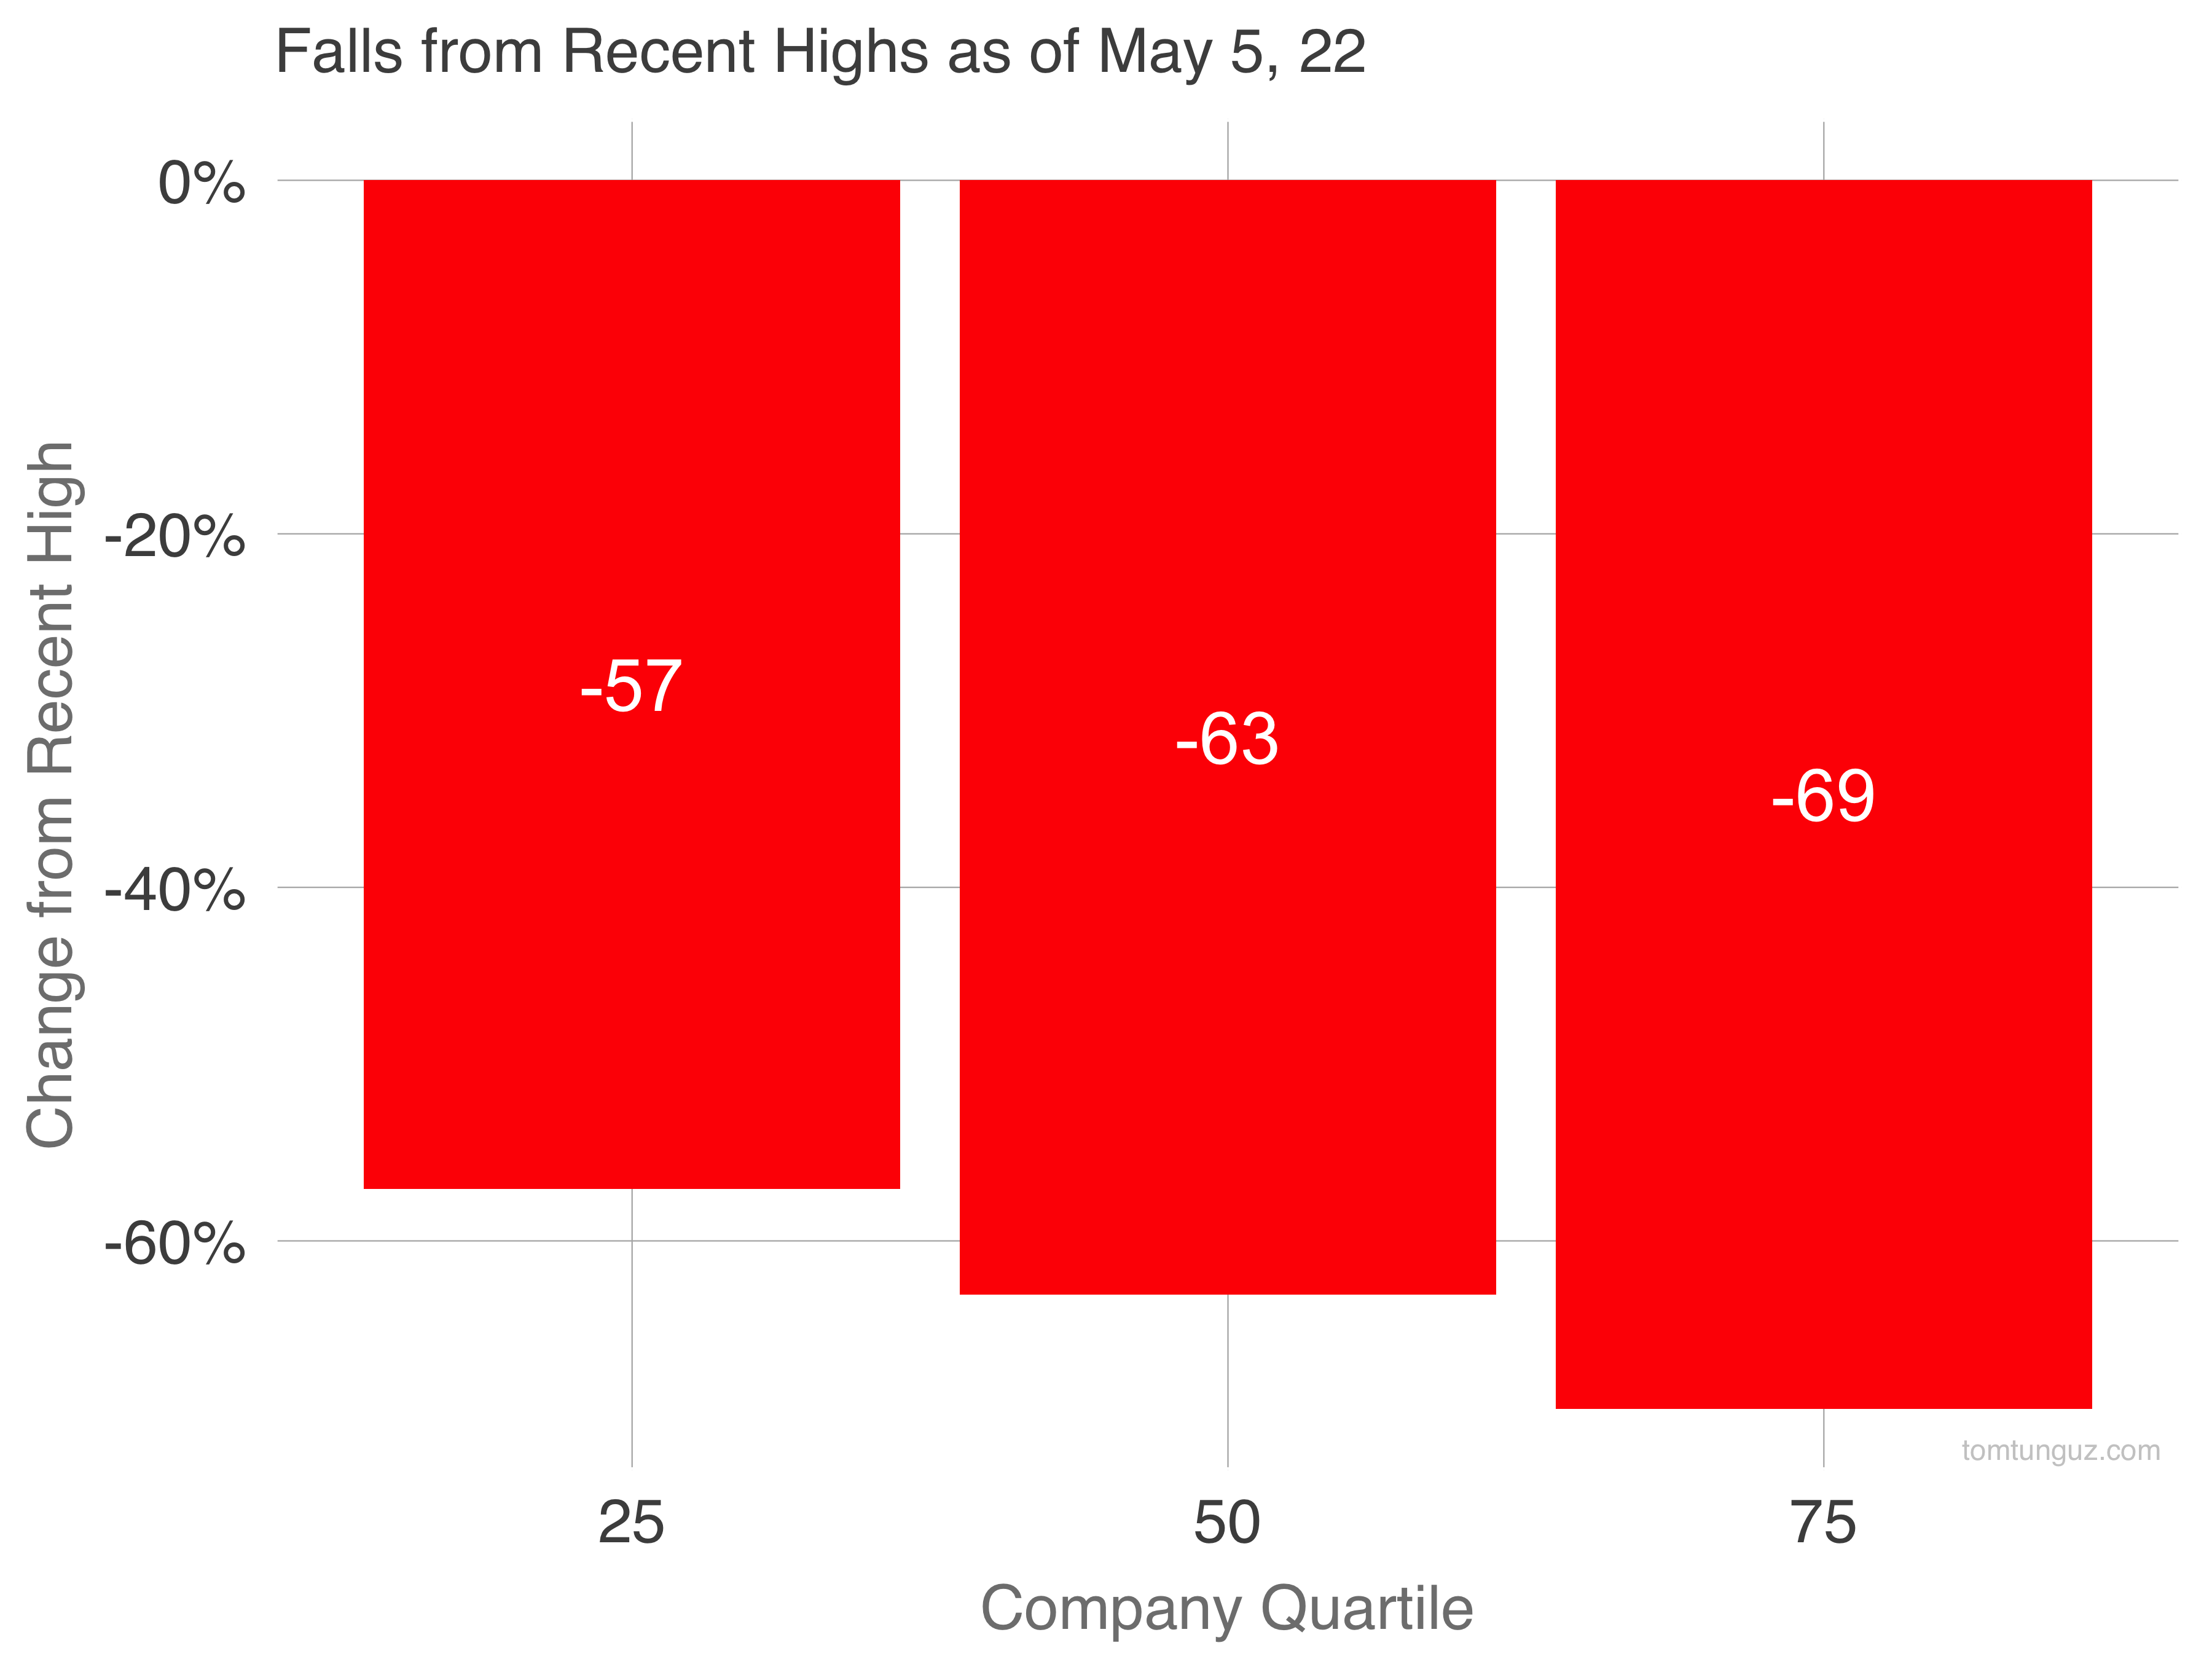
Public companies can’t hide from the 70% collapse in multiples the way startups can. Publics are marked to market daily. Big acquirers walking through the aisles of the stock exchanges are staring at buy-one-get-one-free specials.

Read more

2022 Startup Market Conditions Survey

Today, I’m kicking off the 2022 Startup Market Conditions Survey to assess how startups are feeling about the market given all the volatility.

If you’re interested to participate, click here.

The survey has 16 questions. I’m looking to understand how startups are feeling about their financial outlook, fundraising, new employee hiring, and strategic options (sale, inside rounds, venture debt).

I’ll close the survey in a week and publish the results shortly thereafter. If you have questions, just email me.

Read more

Lessons from Watching a Great CEO Operate

From every startup I work with, I learn about the different ways of building a company. It’s one of the best parts of the job. By their nature, founders hold strong world views about how to craft their companies.

Though it’s early in the company’s life still, Barr Moses, the founder and CEO of Monte Carlo, is an extraordinary leader.

Many startups face a strategic question early on of whether to create a new category. It’s a heavy lift. A former executive at Gainsight which created customer success, Barr jumped in. Monte Carlo is creating the data observability space.

Read more

So You Want to Improve Your Sales Efficiency

With all the talk of recession, changing market dynamics, and the importance of efficient growth, many teams will be looking to boost their sales efficiency. How can the company drive more sales with less expense?

Let’s start with the formula for sales efficiency.

Sales efficiency = New_Bookings x Gross_Margin / Sales_and_Marketing_Cost

Three paths emerge from the equation:

  1. Increase bookings: increase pricing without sacrificing sales velocity.
  2. Improve gross margins: reduce infrastructure spending, eliminate software bills, and/or reduce customer success costs.
  3. Decrease sales & marketing cost: increase quotas, focus on marketing channels with superior ROI (at the expense of exploration), and improve sales training/support.

Each strategy is viable. Teams should select the path or combination that suits their business best. But these strategies won’t impact the sales efficiency number the same way. Why? Convexity.
Read more
The 4 Startup States During a Recession

The 4 Startup States During a Recession

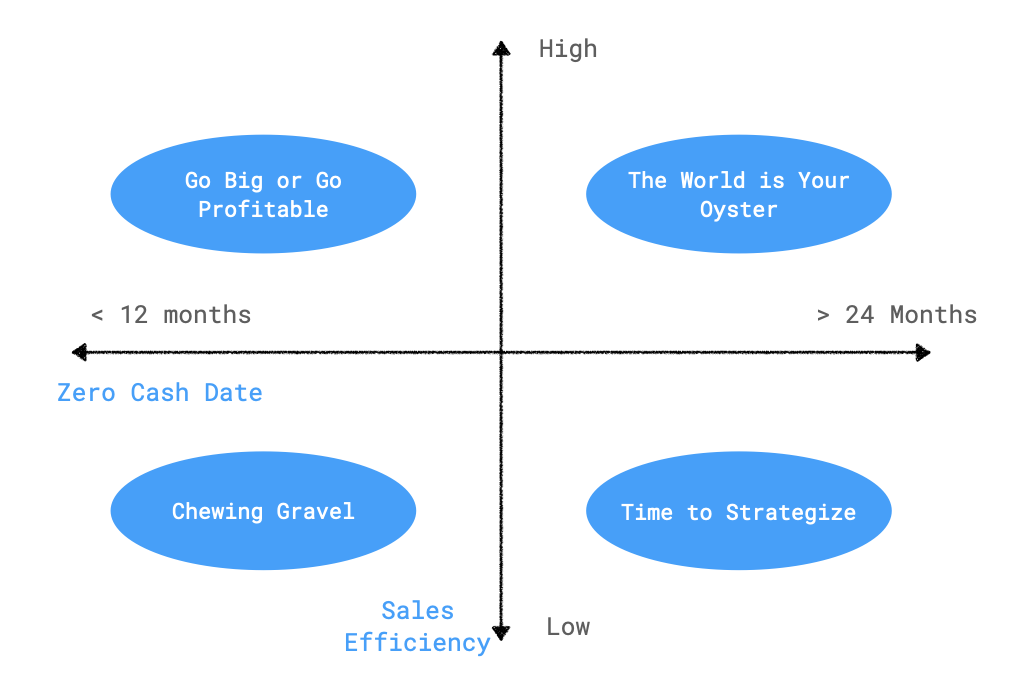
As the fiscal quarters of many startups draw to a close, board members and management teams are having one of four conversations: The World is Your Oyster, Time to Strategize, Chewing Gravel, or Go Big/Go Profitable.

image

Here’s how these scenarios fall onto a 2x2 matrix. The x-axis is the Zero Cash Date: when the startup runs out of money. The y-axis is sales efficiency: a proxy for product-market fit (PMF). Typically, most startups selling into the small-and-medium business segment would like to be in 14-18 months’ payback. Enterprise startups should be between 18-28 months.

Read more

Five Mid-Year Predictions for Web3

The past three days may be the most eventful in web3 ever. Crypto assets have fallen by half or more, following their software counterparts. The attack on an algorithmic stablecoin’s peg harkens back to Druckenmiller breaking the Bank of England.

All the tumult in the crypto markets will catalyze change. Here are my five mid-year predictions for the major evolutions that arise in response.

  1. Consolidation. Five to ten L1s emerge as leaders driven by apps that attract users and net new GDP into their ecosystems. More dollars and users incite a positive feedback loop reinforcing the dominance of these L1s. In Defi, Lindy’s Law rules: institutional investors opt for protocols with the longest track records. Crypto-gaming succeeds in bringing 100m users to web3, starting with casual games which are easier to build, experiment, and iterate. AAA gaming titles arrive two to three years later because of their development lifecycles and studio risk aversion to invest tens of millions into a new platform.

  2. Money pours into web3. Despite the volatility rollercoaster, regulation inspires confidence in web3. Institutional capital floods the market fueled by Dramamine and greed. Unable to general positive yield from bonds because of inflation, fixed income investors pivot to staking to outperform the market. VCs revel in the short term liquidity reminiscent of the late 1990s when startups went public in fewer than 4 years. Spectacular booms and busts continue.

  3. Regulation. Basel IV will mandate that any stablecoin issuer become a bank and keep a minimum level of tier 1 and 2 capital. The first three Basel Accords set the minimum amount of capital a bank must hold. Each Basel Accord was authored in response to a crisis Basel I - the crash of 1989; Basel II - the dotcom crash, and Basel III - the GFC of 2008. The US Government enacts the Securities Act of 2023 to regulate crypto assets: their sale, their construction, FDIC admittance for stablecoins, and the establishment of a new regulatory body modeled on the the Securities Act of 1933.

  4. Tokens ape stock rights; DAOs mimic boards of directors. Token holders demand dividend/revenue share rights in addition to voting. Investors start to value tokens on fundamentals. The 1/9/90 dynamic observed in DAOs consolidates voting power into a few delegates, which mirrors public company voting and board election. Tokens and DAOs remain distinct from stocks and boards because of the regulatory arbitrage that enables startups to go public in half the time of the classic route. But they serve effectively the same purpose. Utility tokens disappear to the end user replaced either by a stablecoin or an ecosystem reserve currency.

  5. Token cap tables mirror equity cap tables. Web3 companies relax the fixed employee token allocation. DAOs issue periodic governance requests to increase the employee token pool to incentivize employees. The share of networks sold to investors asymptotes that of a web2 company at IPO, but it remains distributed across a broad institutional base and some retail investors.

Read more