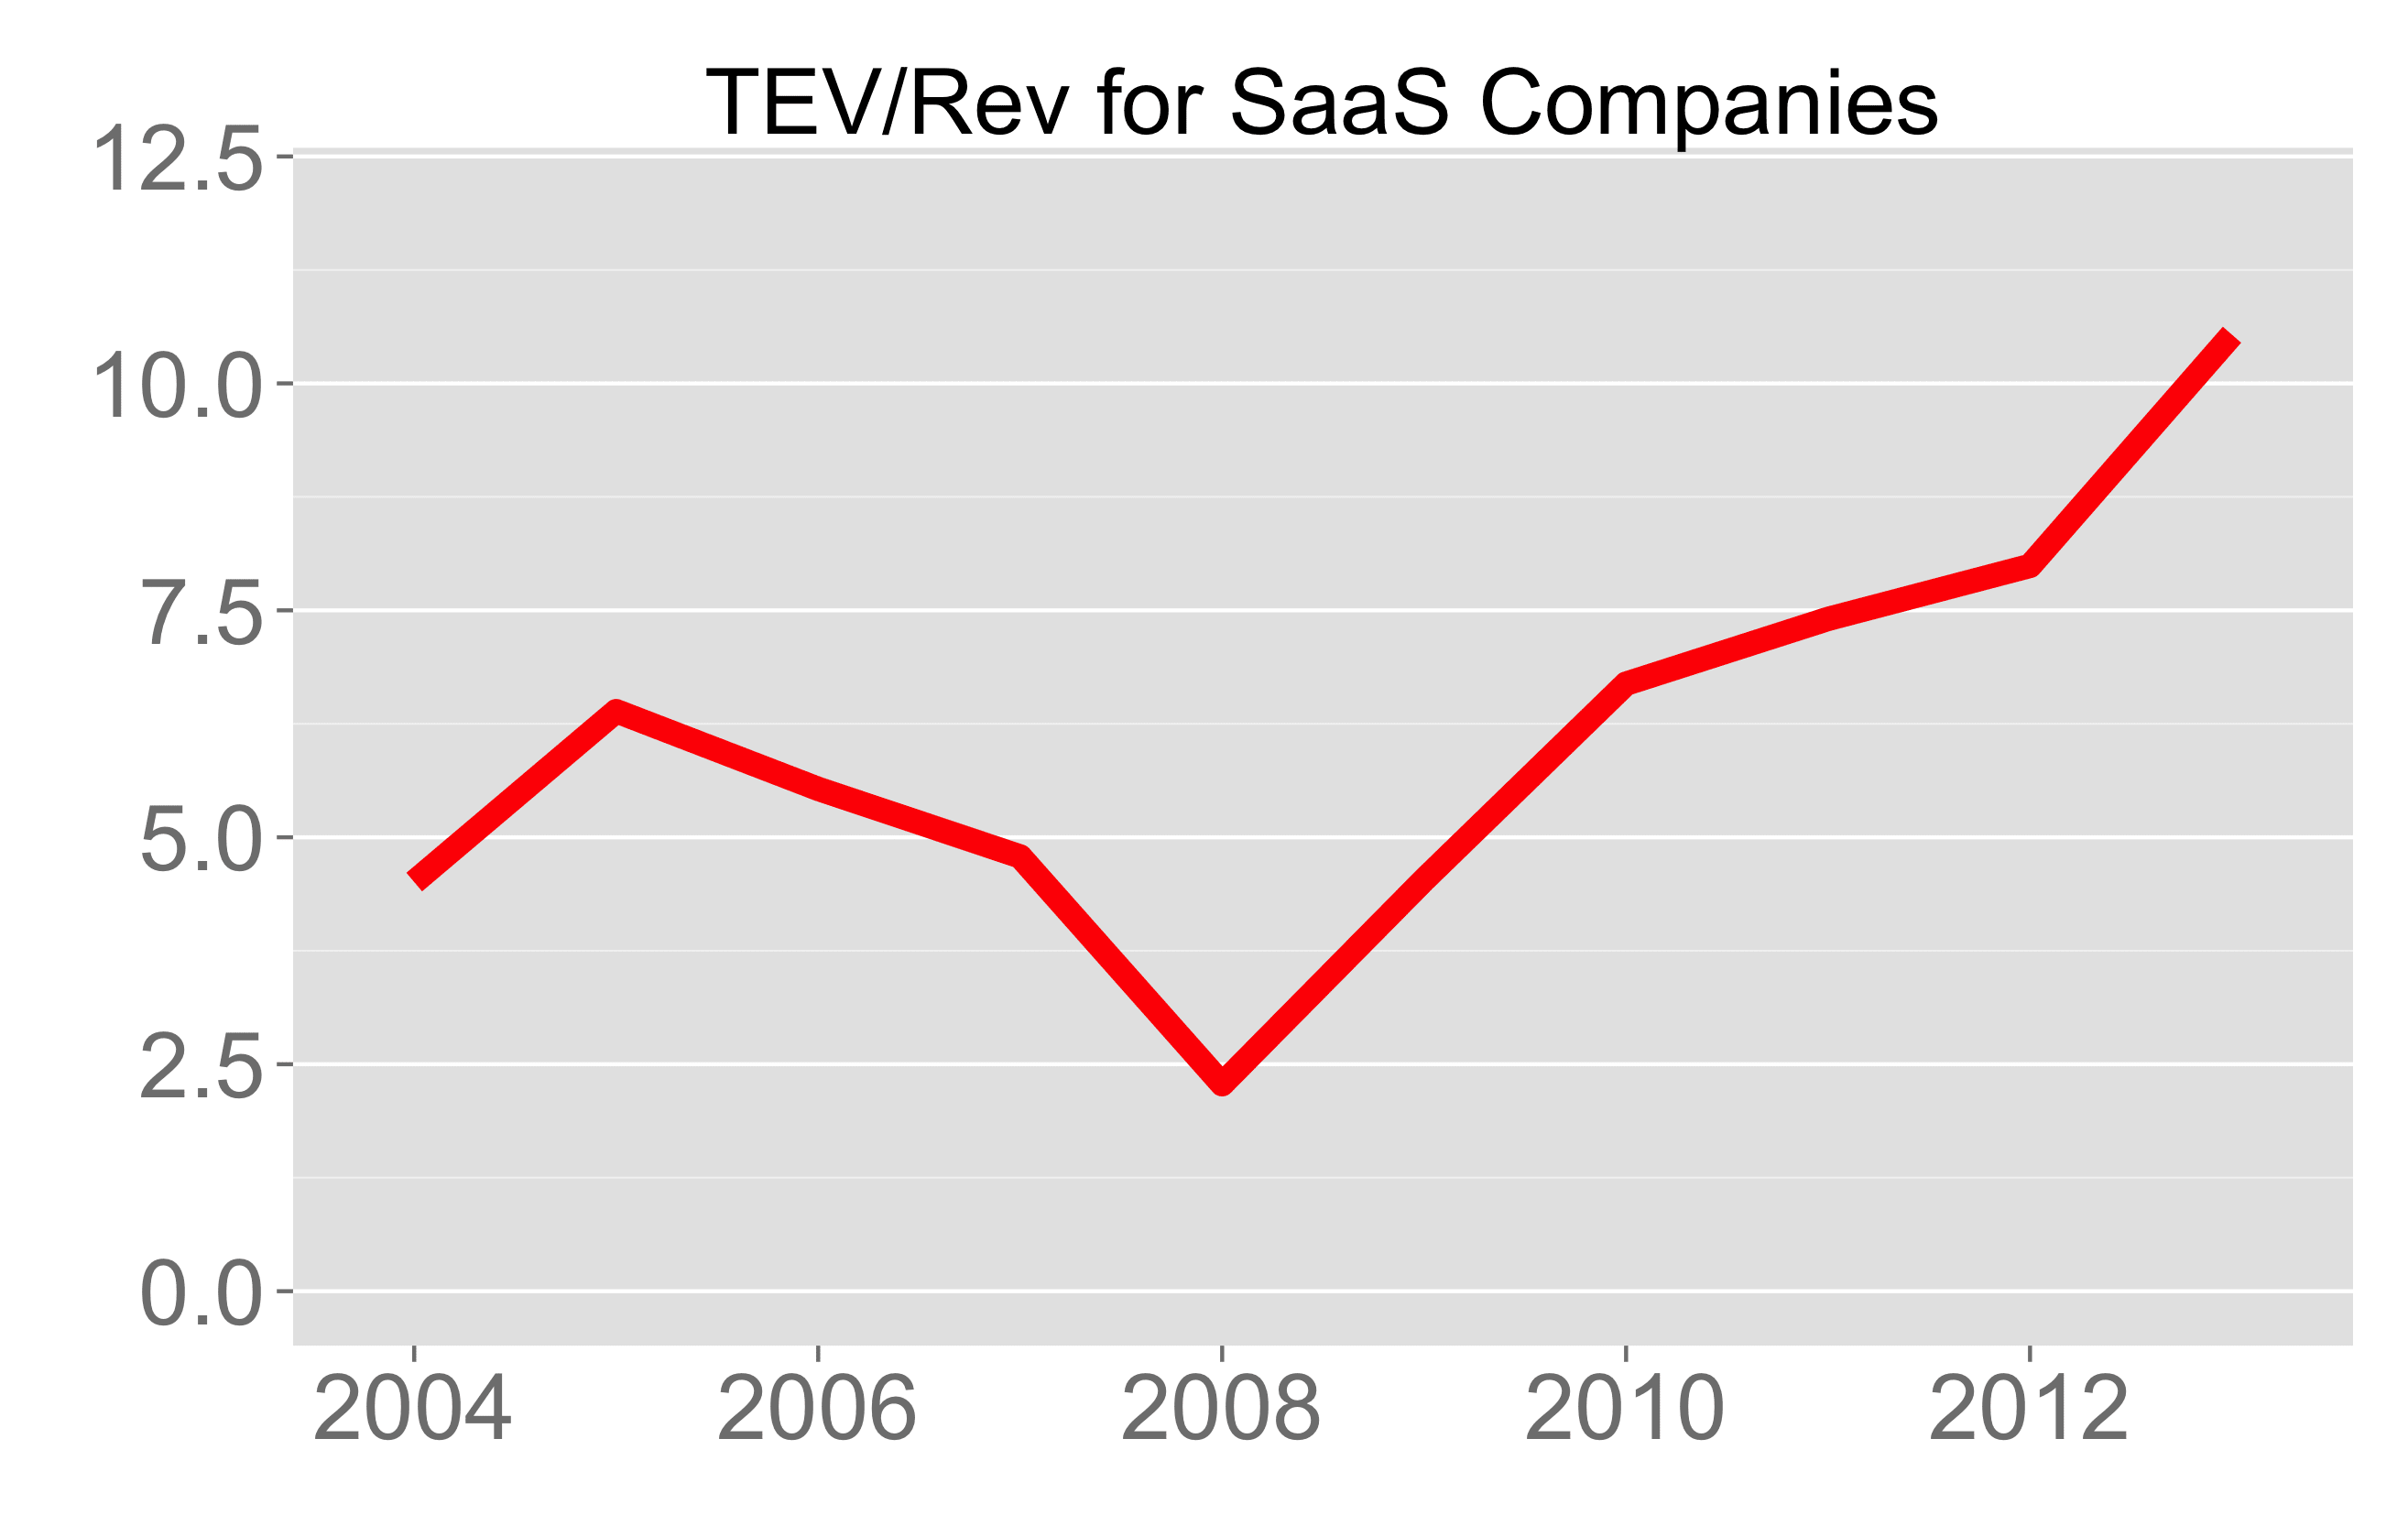
Benchmarking Box's S-1 - How 7 Key SaaS Metrics Stack Up

Yesterday, Box filed for its IPO and released its S-1. I enjoy going through S-1s because quite a bit about a private company is revealed and though only a subset of information is released, the S-1 discloses some very important details about the business operations.

Over the past several months, I’ve analyzed the basket of the roughly 40 public SaaS companies many different ways. With the Box S-1 in hand, I can now benchmark Box’s business against other publics, and in particular, SaaS companies nine years after founding. Box is also nine years old. Below are seven key comparisons between Box and the average public SaaS business.
Read more

Startup Best Practices 6 - Avoiding the Bike Rack Effect

Imagine a city council meeting with three agenda items: a $100M power plant zoning approval, a request to build a $10,000 bike rack for city sidewalks and and a $100 proposal to buy refreshments for the annual picnic. The power plant discussion takes all of 3 minutes to reach approval, as does the refreshment budget. But the $1000 bike rack debate drags on for hours as council members debate the right materials, the best color scheme and the right way to announce the project.

Read more
The Hardest Round to Raise for Startups

The Hardest Round to Raise for Startups

image

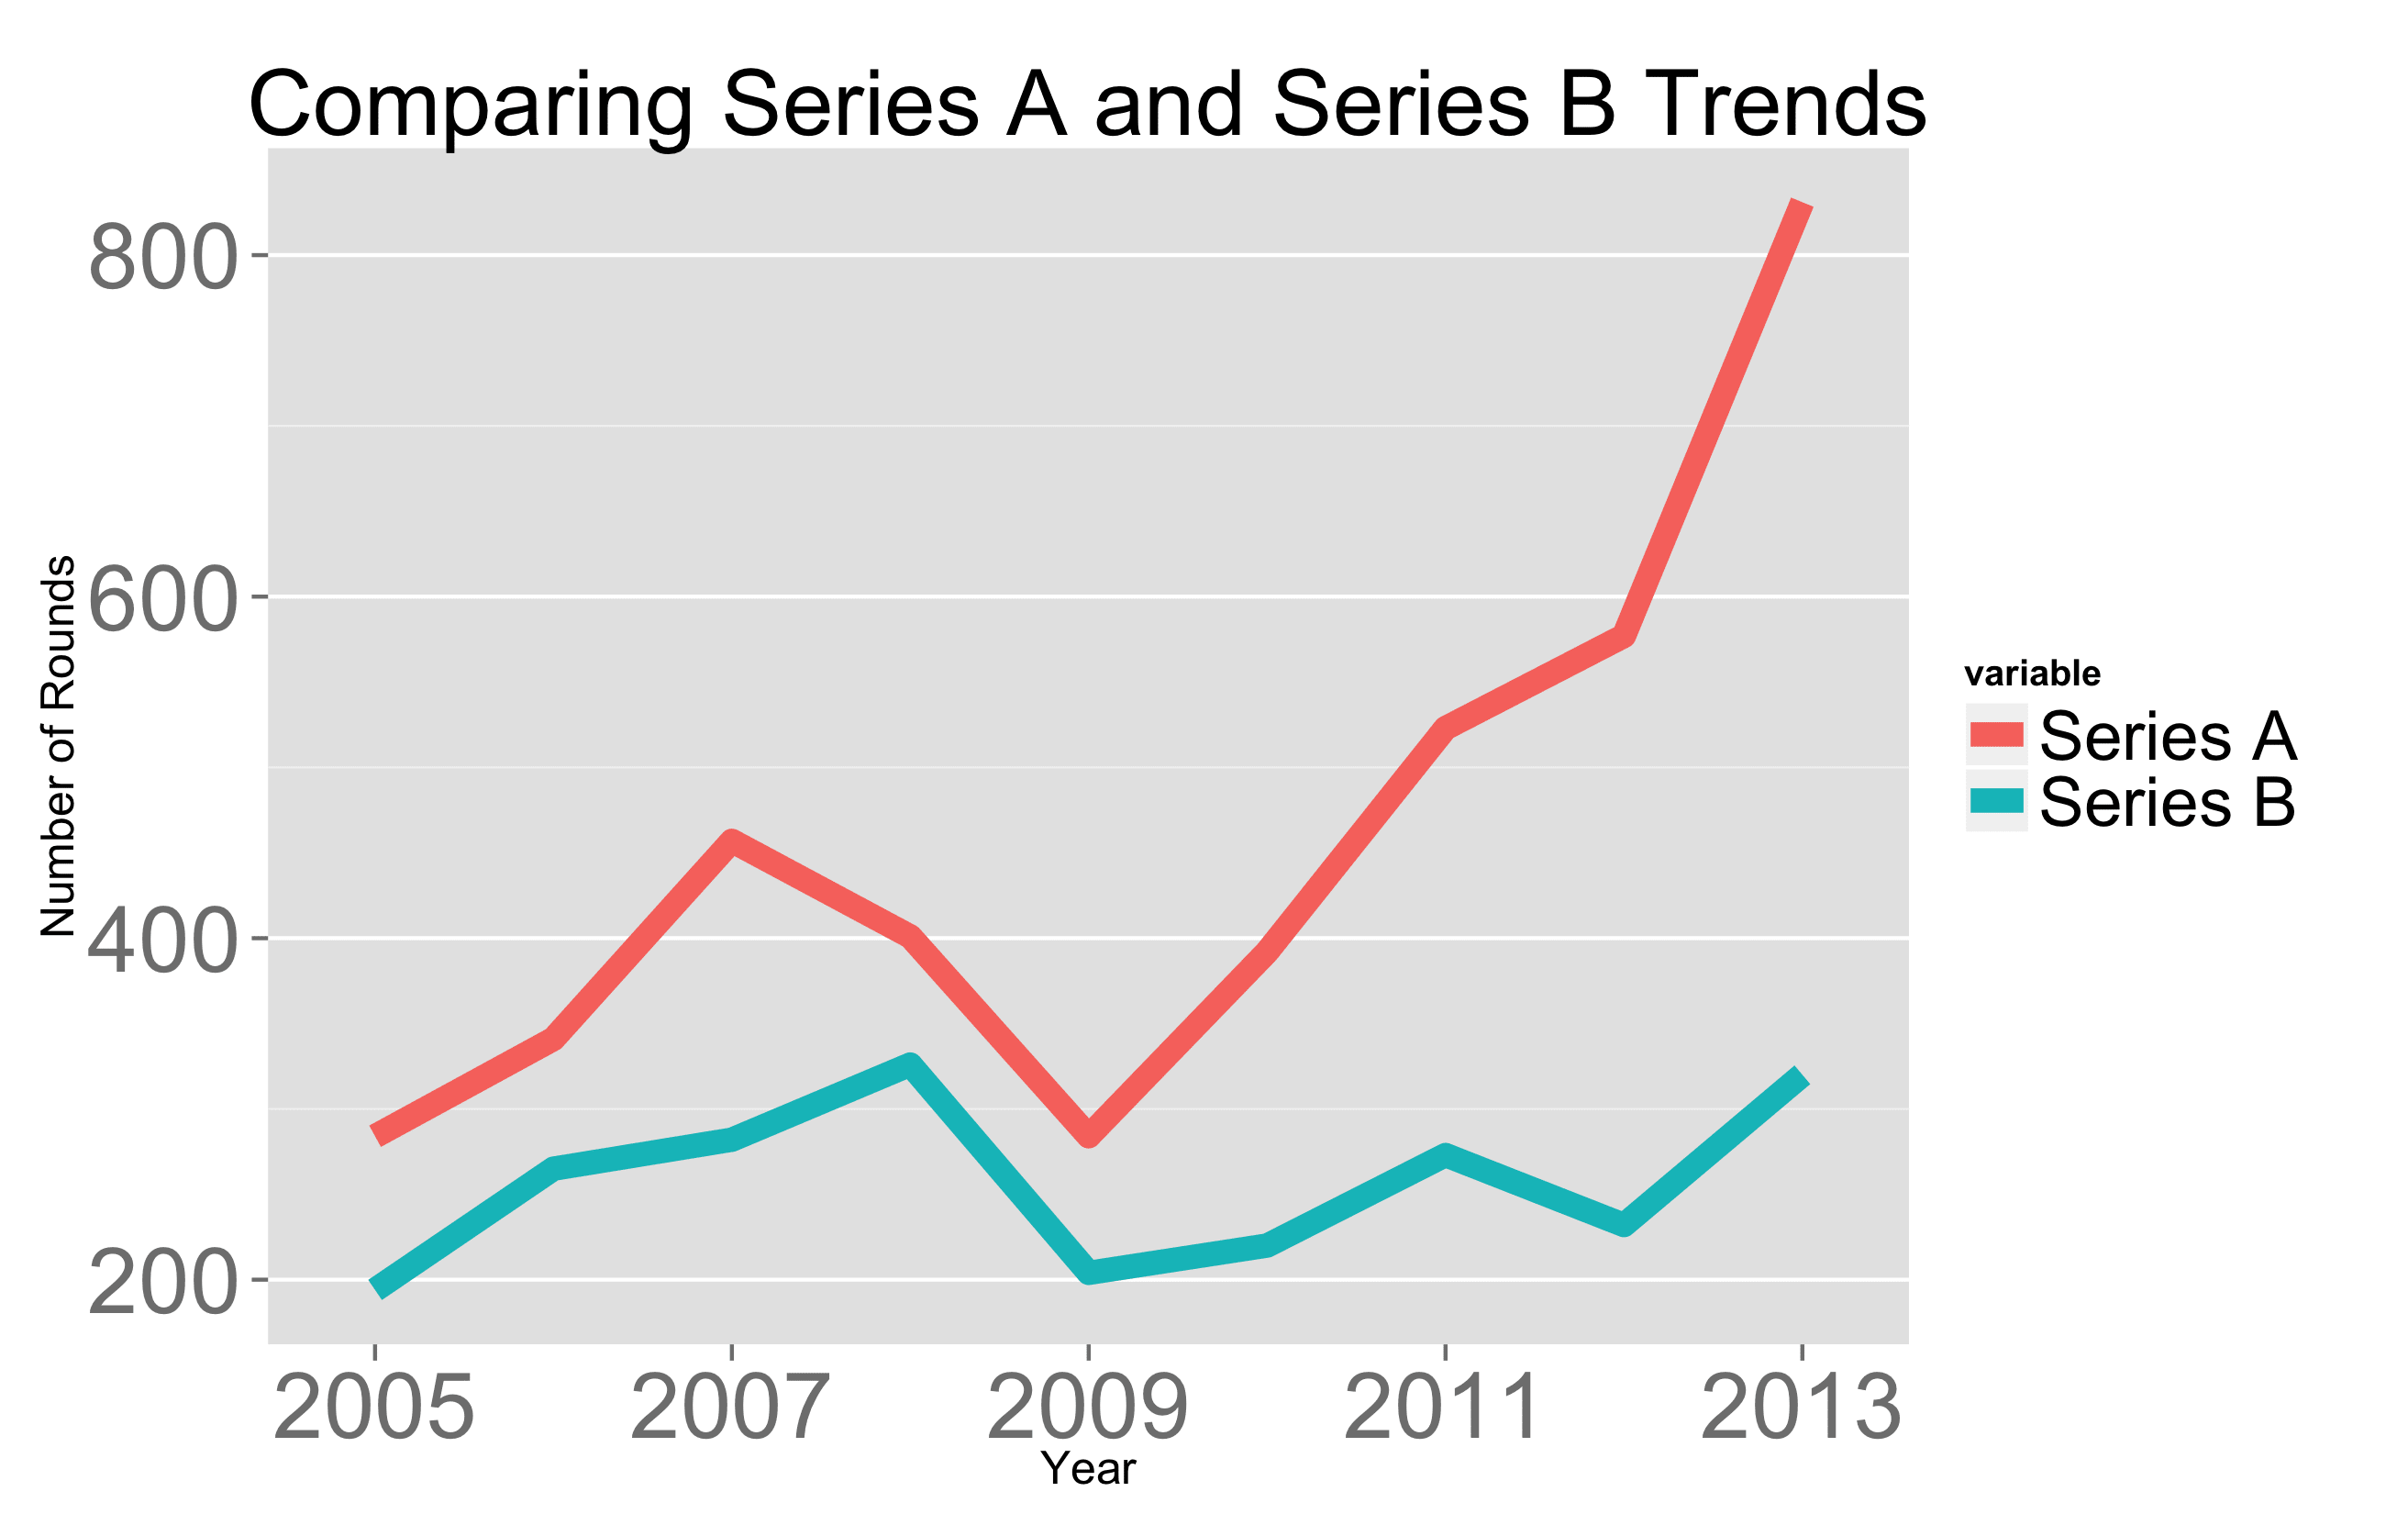
Over the past few years, I’ve debated the existence of a Series A crunch and found in that analysis that the volume of Series As was increasing. This trend hasn’t abated. The number of Series As has grown by 31% annually for the past 5 years, reaching more than 831 Series As in 2013, up from 284 in 2009. In short, no founder should be concerned about the Series A market.

Read more
The Machinery of Blogging

The Machinery of Blogging

image

I’ve been getting a few questions about the tools I use to publish this blog, so I figured I’d write about it and reveal the machinery behind the curtain. I use four main tools Jekyll, Github Mou, and RStudio. Jekyll is the blogging engine; Github is the hosting provider; Mou is the app I use to write these posts; and RStudio is the place I analyze data and make charts.

Read more
Are VC Mega-Rounds the New Normal?

Are VC Mega-Rounds the New Normal?

image

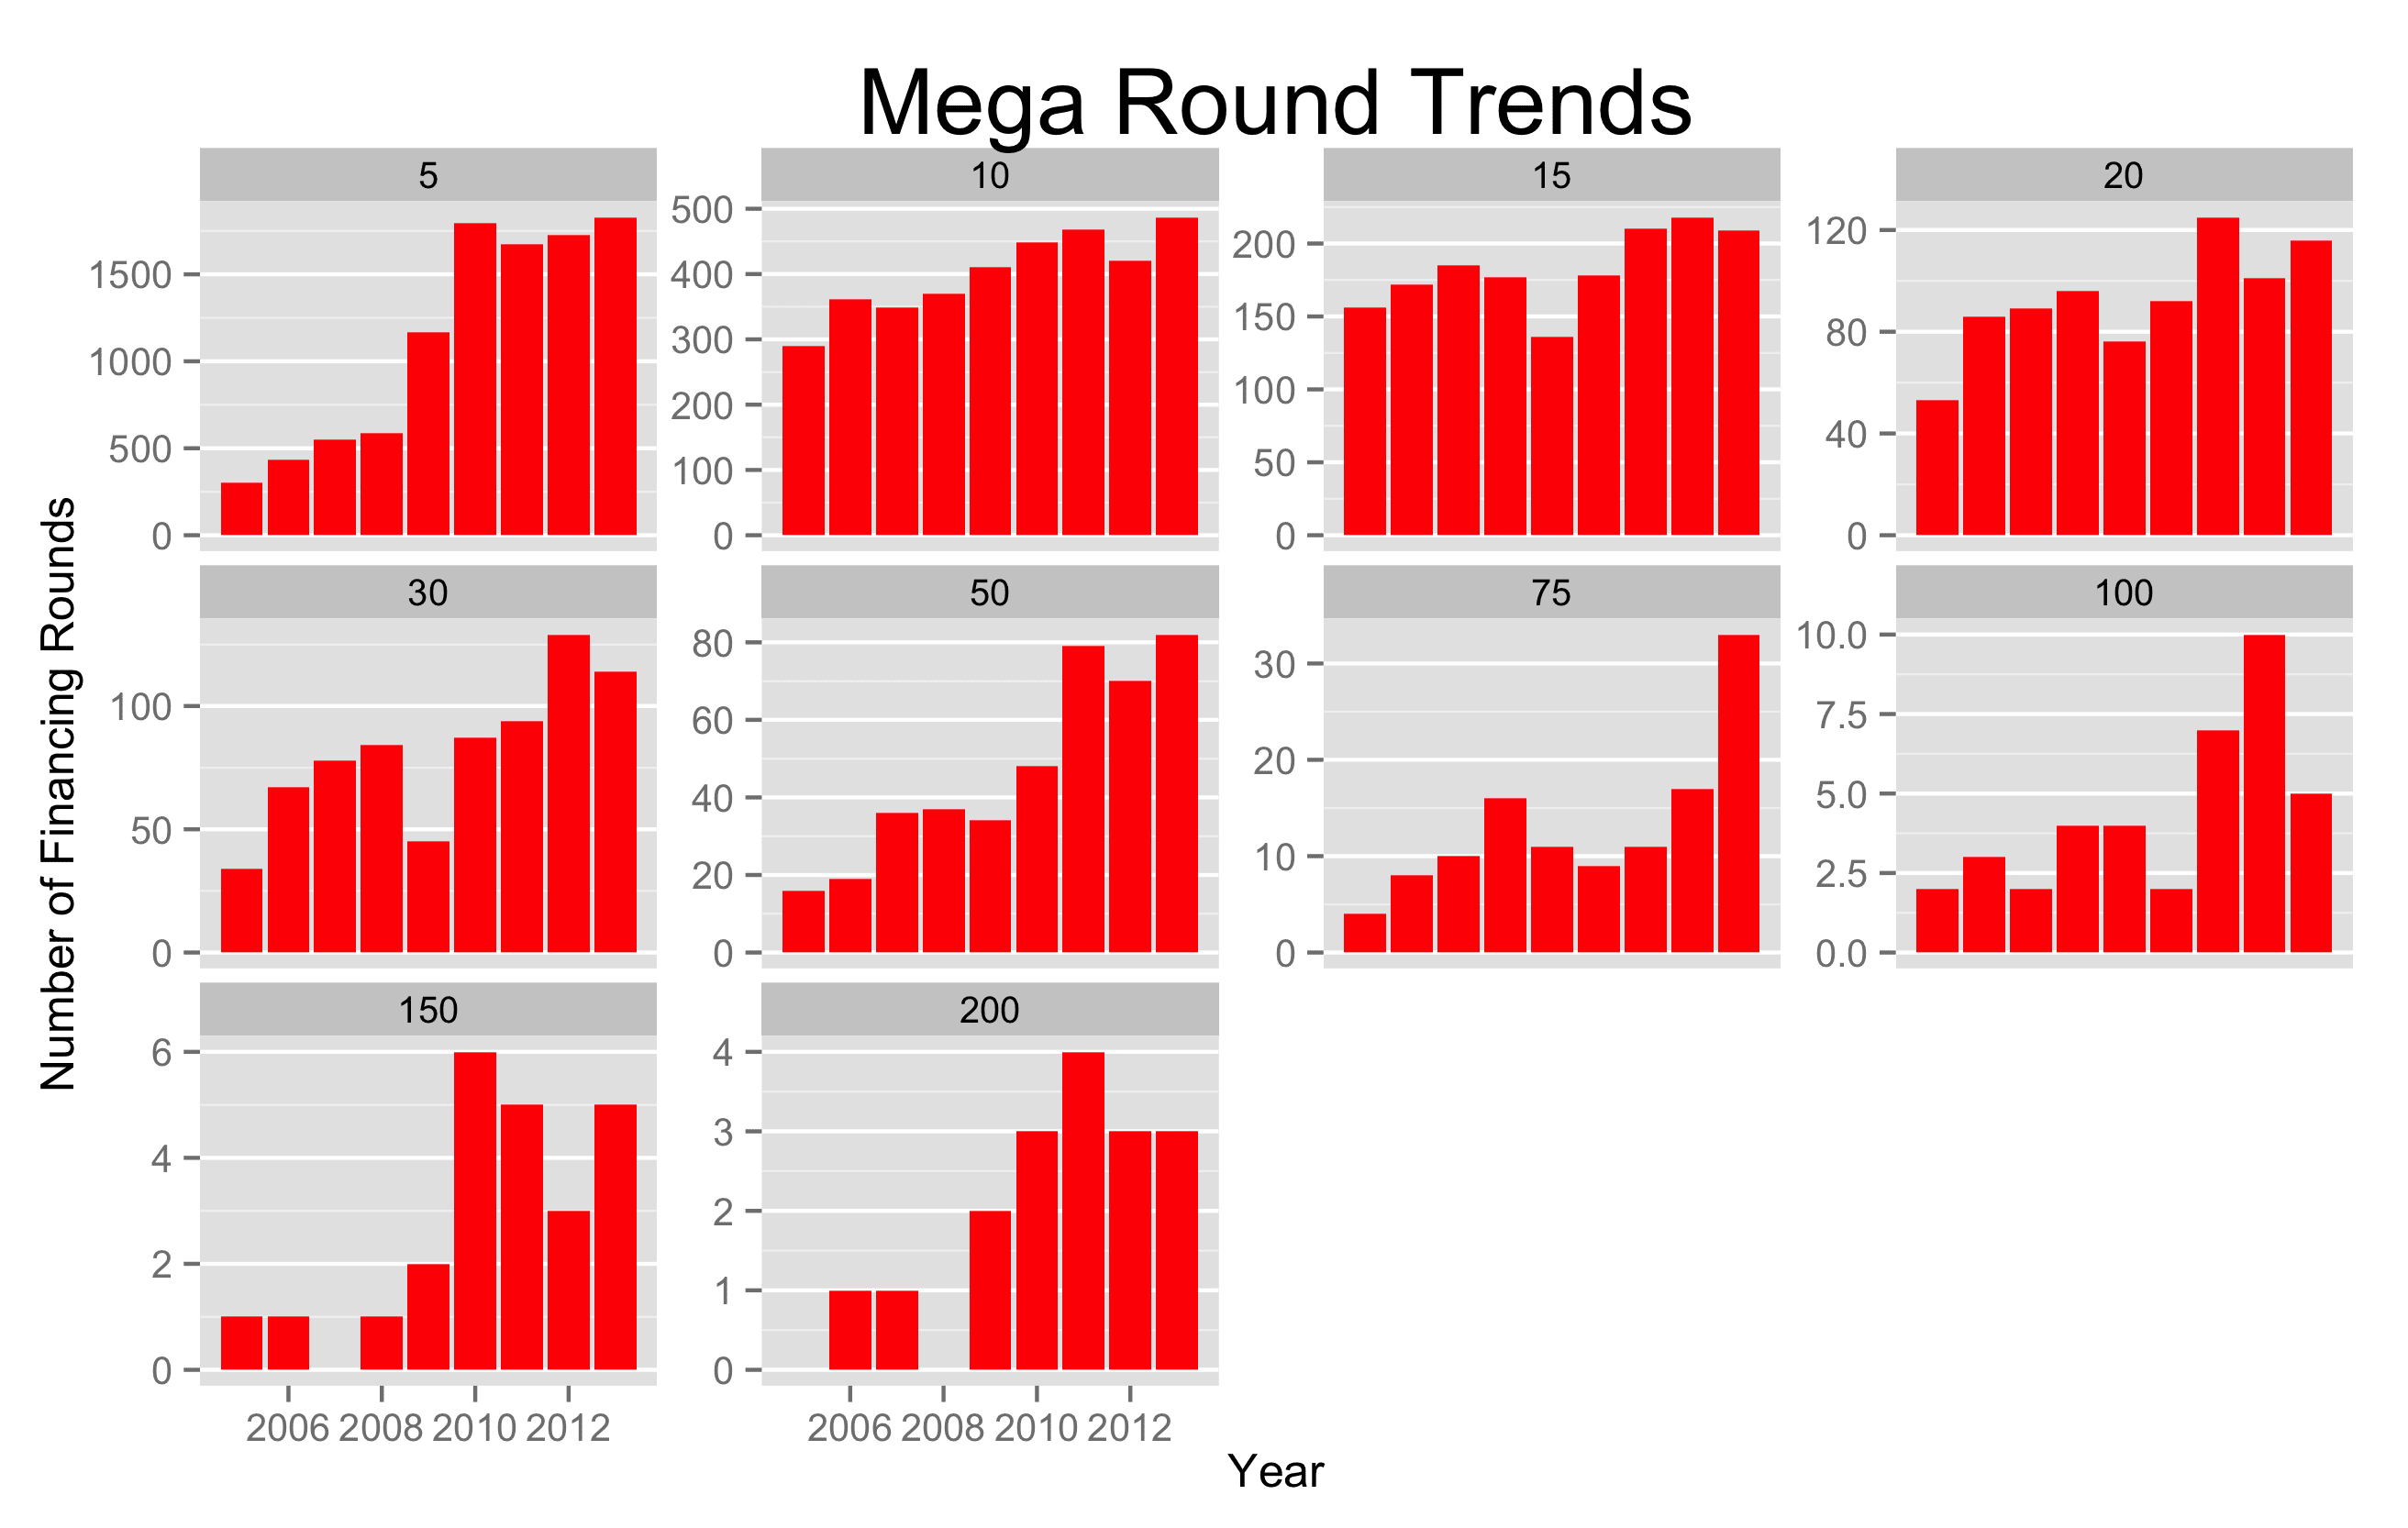
Each morning’s news seems to bring another fund-raising announcement of ever larger scale. Just a few months ago, Pure Storage raised $150M in the largest ever venture investment in a storage company. These record financings certainly generate significant press interest. But how representative of the fund raising environment are these mega-rounds?

The chart above breaks down fund-raising activity in US tech companies using Crunchbase data. Each chart shows the number of rounds raised bucketed by size from $0 to $5M and up to $150M to $200M from 2005 to 2013.

Read more
SaaS Startup Balance Sheets: How Much Cash & How Much Debt to Raise

SaaS Startup Balance Sheets: How Much Cash & How Much Debt to Raise

image

After reading a few of the S-1 analyses on this blog, an entrepreneur asked me to look into the balance sheets of public SaaS companies. More specifically, how much cash should SaaS hold? How much equity do they raise? And do they employ debt to grow?

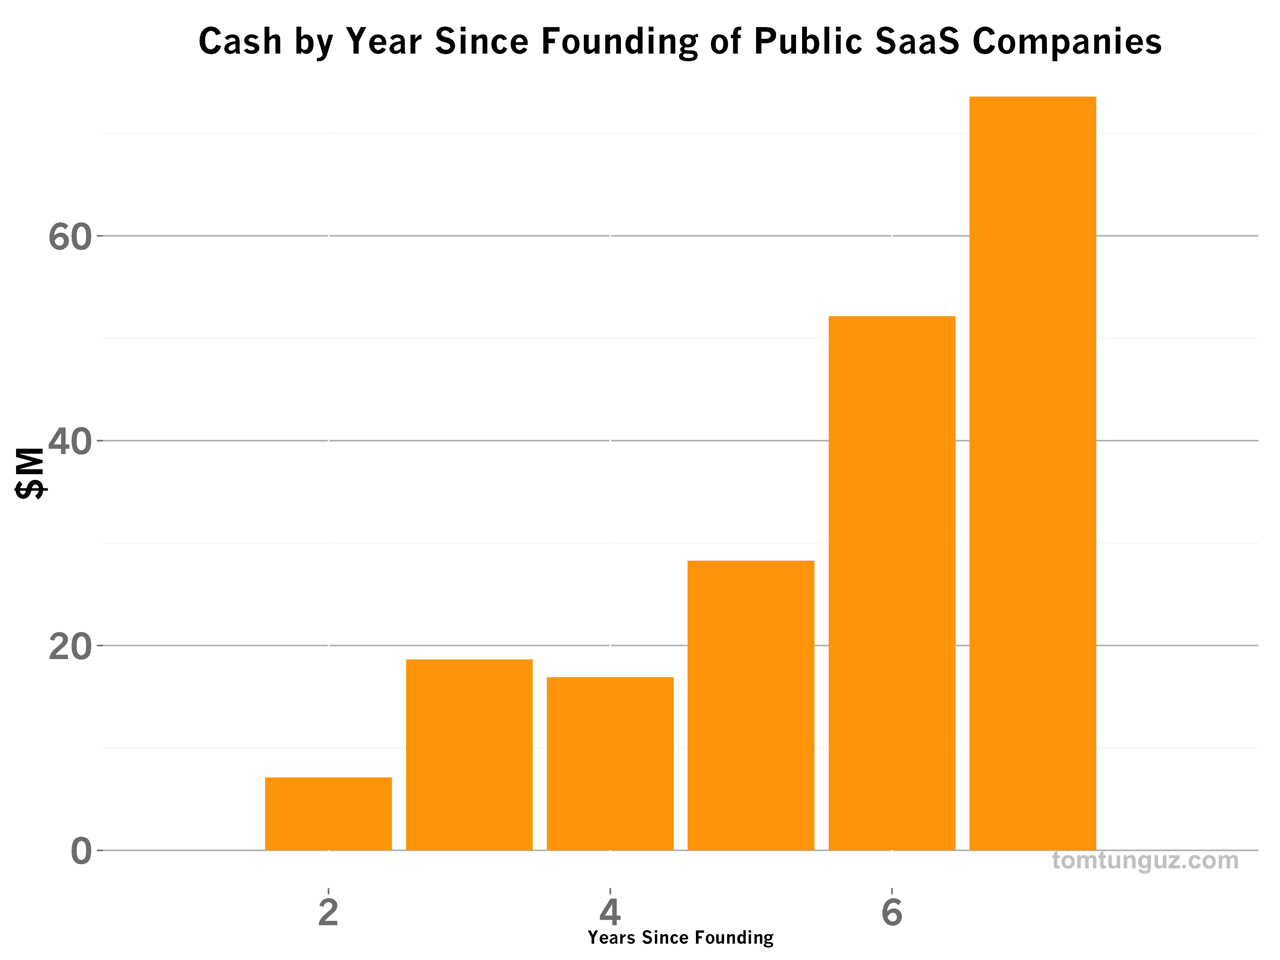
The chart above shows the median cash on the balance sheet by year of founding for publicly traded SaaS companies. By its second year in business, the median SaaS company in this data has about $7M on its balance sheet at year two, from either the combination of a large seed round and Series A, or just a large A. The company grows quickly enough to raise a $12-$25M Series B in the next 12-18 months, which is year 3 or 4 in the company’s life. The business deploys that capital to continue growth at which point it raises another $20-30M in its Series C in year five, and another $20-$30M in year six which should be the final round before IPO. Most often, SaaS publics IPO in year seven, but this figure varies quite a bit.

Read more
How Quickly Does a SaaS Startup Have to Grow to Go Public?

How Quickly Does a SaaS Startup Have to Grow to Go Public?

At the time of the IPO, the median Software-as-a-Service (SaaS) company generates $100M in revenue, creates $2.6M in profit and holds $85M in cash on the balance sheet. A company in this position typically raises $107M in its IPO and trades at 11x revenue, for a $1.1B market cap.

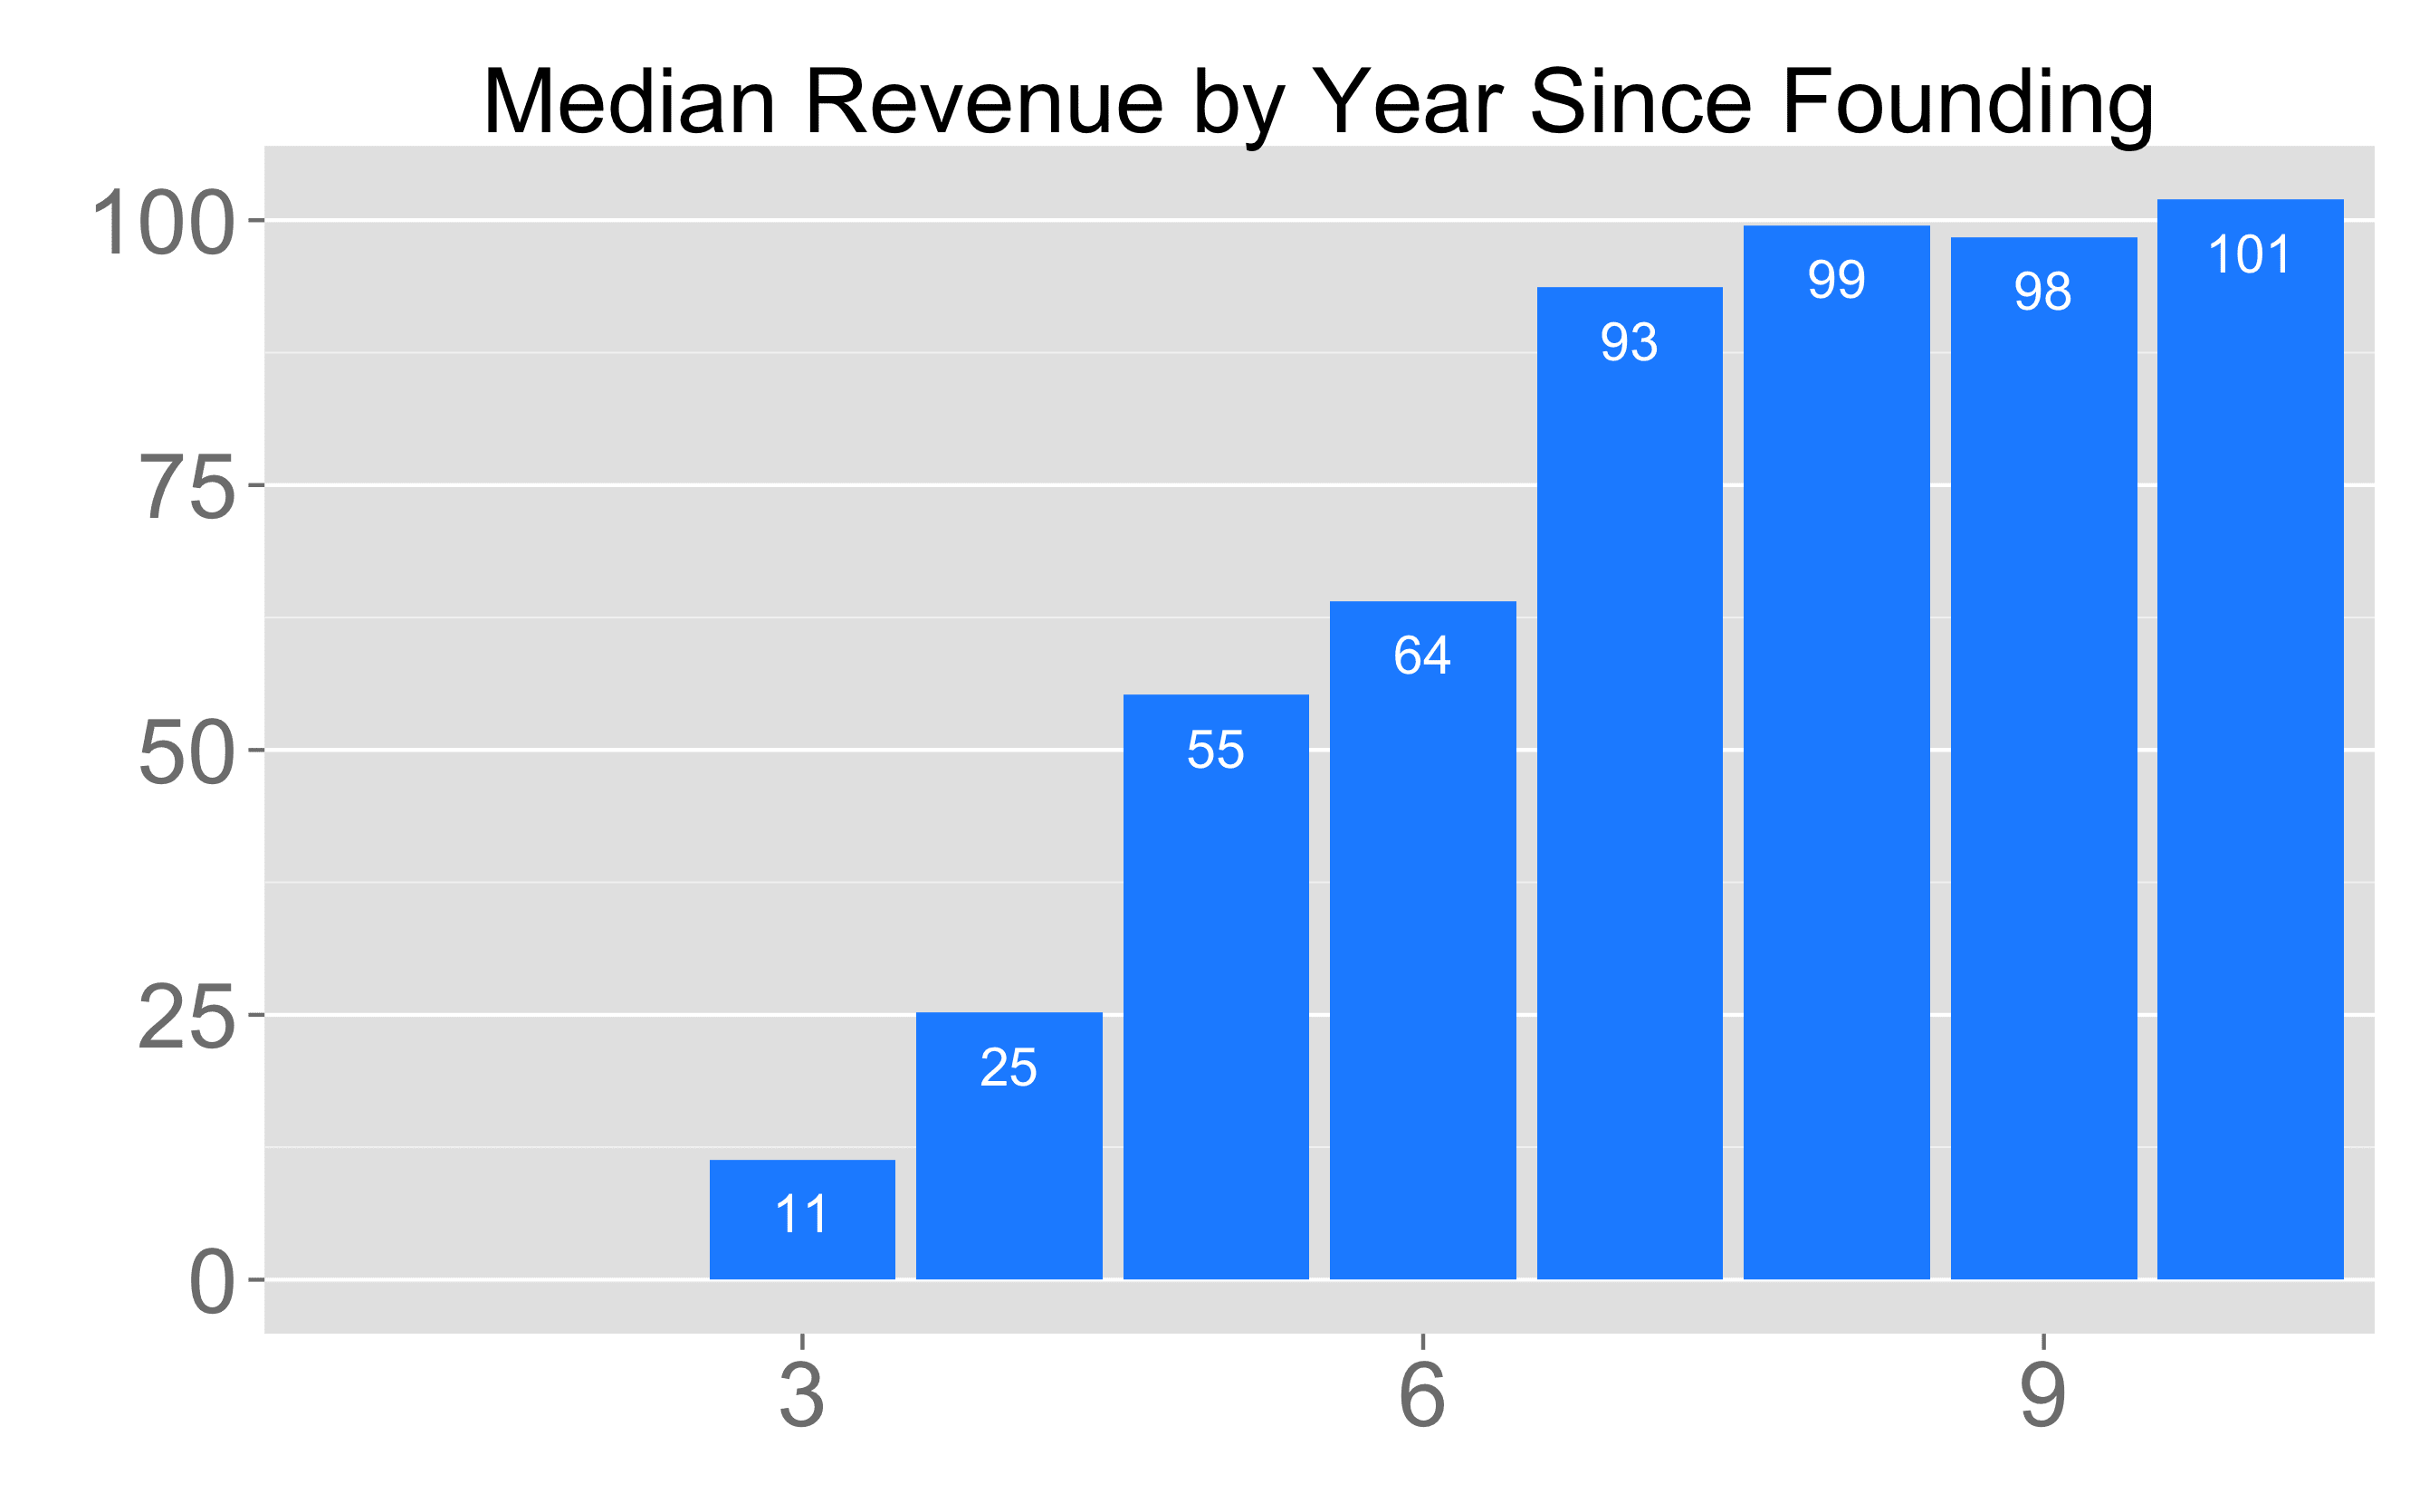
The path to getting there is revealing. Below is a chart showing the median revenue ramp of the 41 publicly traded SaaS companies by year since founding. In year 3, the median revenue is $11M. In year 4, the revenue figures more than double to $25M, and then again to $55M.

Read more
Why There's Never Been a Better Time to Found a SaaS Startup

Why There's Never Been a Better Time to Found a SaaS Startup

SaaS companies are the darlings of the public market. The average publicly traded SaaS company enjoys twice as strong a revenue multiple as ten years ago. SaaS companies’ time to IPO has been decreasing steadily from over 10 years since founding to under 7. Despite the decrease in time to IPO, the average dollars raised at IPO has tripled from the early nineties and grown by 50% since 2000.

I analyzed the 41 publicly traded SaaS companies comparing to understand the trends in SaaS IPO. The data set is here. Here are four charts depicting the trends.

Read more

The New Market Places

One of the most important trends in the Internet at the moment is unbundling. Entrepreneurs are picking apart Craigslist and eBay, vertical by vertical. At the same time, other entrepreneurs have replicated the core functions and features of Facebook and LinkedIn, creating hugely valuable companies.

But simply calling this trend unbundling doesn’t do the movement justice, particularly in the transactional web. The trend is more fundamental.

Craigslist and eBay are the canonical internet market places. Craigslist is synonymous with internet classifieds. eBay coupled a payments system to the listings model, enabling user-to-user transactions at scale. Both eBay and Craigslist exposed the buyer to the seller in a transparent way. They avoid arbitrating or regulating disputes as much as possible, and push as much of the negotiation and price discovery as possible to the buyer and seller. For this, eBay charges 10% of gross merchandise value. Both companies provide large amounts of liquidity, a little bit of advice and take a relatively small stake of the transaction value.

Read more